What Most People Get Wrong About This
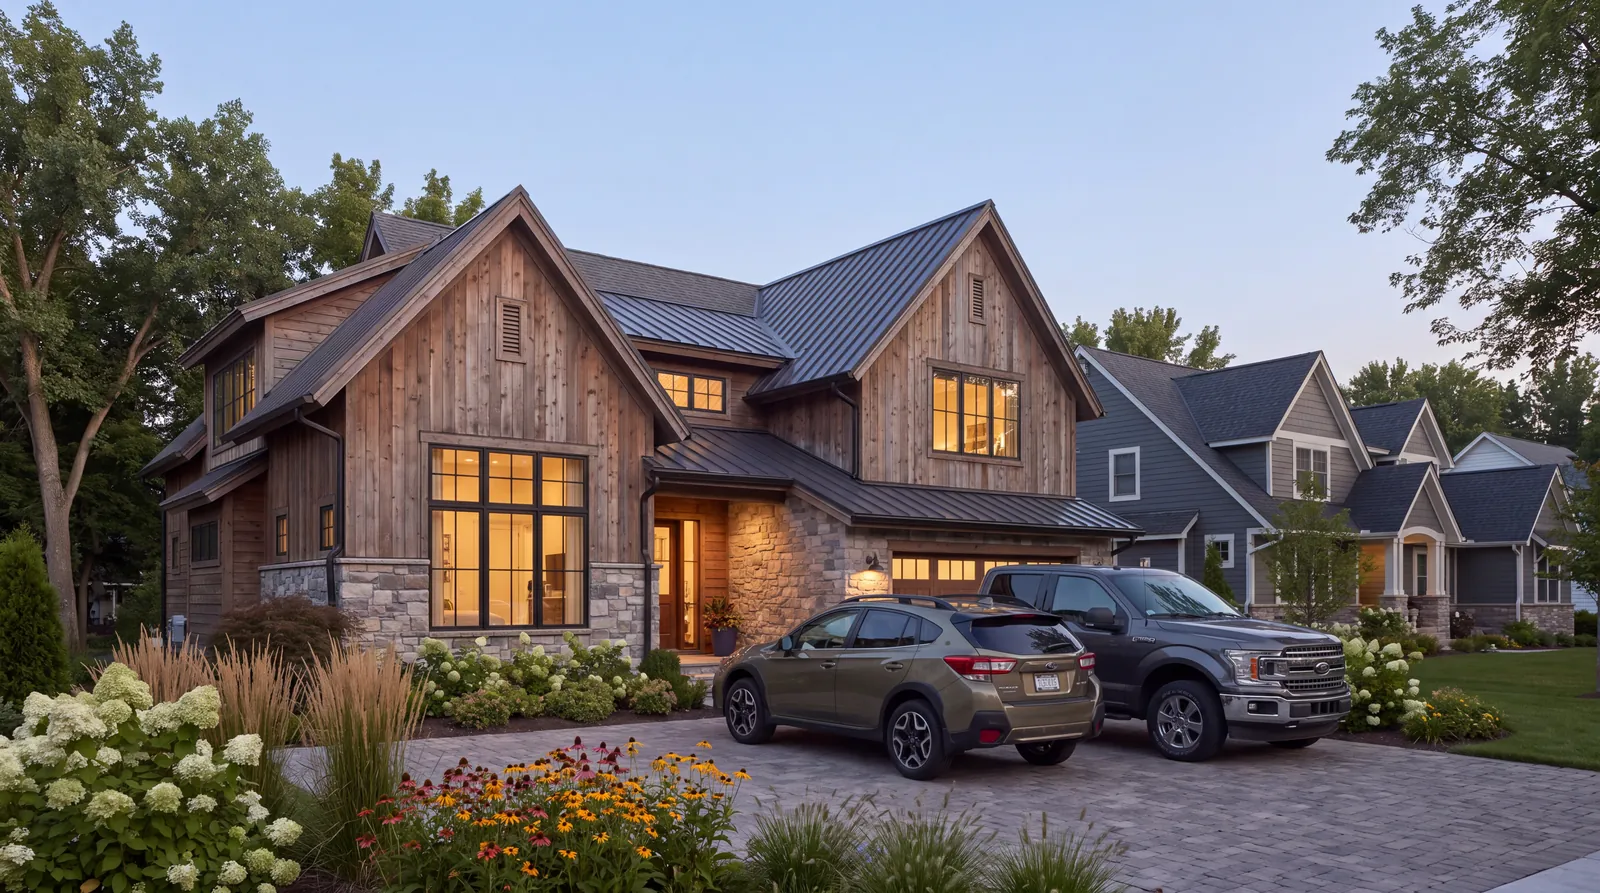
The usual line: Eagan is a newer suburb, so the house is newer too. The roof is probably fine, the plumbing is modern, and a homeowners policy here is a formality.
What's actually true: Eagan grew up fast in the 1970s, '80s and '90s, and those homes are now roughly 27 to 56 years old. The Census Bureau's latest five-year estimates put the median Eagan home's year built at 1988, and only about one home in ten was built in 2010 or later. Many original roofs from that era have likely been replaced or are near the end of their life. Water heaters, supply lines and electrical panels have aged along with them. Minnesota law lets insurers rate on the age of a home's plumbing, electrical, heating and cooling systems (Minn. Stat. 72A.20, subd. 13), so those dates show up in your price.
What to do instead: before you shop, write down three years: when the roof was last replaced, when the major systems were updated, and when you last checked your dwelling limit against today's rebuild cost. Those three numbers do more for an accurate Eagan quote than your ZIP code does.
If you own a home in Eagan, you already know the rhythm: hail warnings in the summer, ice on the eaves in January, and a renewal notice that seems to climb every year. This page is the local companion to our Minnesota homeowners insurance guide. That guide covers how a policy works statewide. This one covers what's specific to Eagan: the age and mix of the homes, what the storm reports actually show for Dakota County, the city's permit rules for roofs and siding, the water you live alongside, and how pricing works inside city limits. Every local figure below names its source, so you can check it yourself.
- Median year built
- 1988Census ACS 2020–2024
- Built 1970–1999
- About 72%Of Eagan housing units
- Median home value
- $397,100Owner-occupied, ACS 2020–2024
- Bodies of water
- 1,200+Managed by the City of Eagan
What does Eagan's housing stock mean for your home insurance?
Short answerMost Eagan homes were built between 1970 and 1999, so roof age, aging systems, rebuild cost and, for the one in five homes that are townhomes, the association's master policy shape your coverage.
Here's how Eagan's 28,789 housing units break down by decade, from the Census Bureau's American Community Survey 2020–2024 five-year estimates (table B25034). Estimates carry a margin of error, so read them as close approximations:
| Year built | Eagan housing units | Share |
|---|---|---|
| 2010 or later | 2,809 | About 10% |
| 2000 to 2009 | 2,594 | 9.0% |
| 1990 to 1999 | 6,583 | 22.9% |
| 1980 to 1989 | 9,658 | 33.5% |
| 1970 to 1979 | 4,557 | 15.8% |
| Before 1970 | 2,588 | 9.0% |
One home in three was built in the 1980s, and the Census puts the median year built at 1988 for both Eagan and Dakota County as a whole (table B25035). Two-thirds of occupied homes are owner-occupied (67.7%), and the median owner-occupied home is valued at $397,100, above the Dakota County median of $381,000, per the Census Bureau's QuickFacts and ACS table B25077. Here's what that profile means when you buy a policy.
The roof is the first question
A house built in 1988 has likely had at least one roof replacement, and some are on their second. Underwriters ask for the roof's age because it drives how a hail claim settles. Some carriers now settle older roofs at actual cash value, meaning replacement cost minus depreciation, rather than full replacement cost. Your declarations page or a roof endorsement will say which applies. Our hail and roof claims guide explains replacement cost versus ACV and the cosmetic-damage exclusions some carriers now use.
Older systems can be rated, but the house's age alone can't
Under Minn. Stat. 72A.20, subd. 13, an insurer can't refuse to write or renew a home, or charge it a different rate, solely because of the age of the primary structure. The same subdivision lets insurers use rating standards based on the age of the plumbing, electrical, heating or cooling system. In plain English: a 1985 house isn't penalized for being from 1985, but a 1985 water heater or electrical panel can count. Keep receipts for system updates and bring them to your quote.
Insure the rebuild, not the sale price
Eagan's median value tells you what homes sell for, which includes the land. Your dwelling limit should reflect what it would cost to rebuild the house at today's labor and material prices. Those can be higher or lower than the sale price. Our statewide guide explains how to set dwelling coverage at rebuild cost.
One home in five is a townhome
The Census counts 5,637 single-family attached homes in Eagan, about 20% of all housing units (table B25024). For those owners, the right policy depends on the association. Where Minnesota's common interest community law applies and units share walls, siding or roofs, the association's property insurance must include the units. It doesn't have to cover interior finishes, flooring, cabinetry or built-in appliances, and the association can pass its deductible to affected owners (Minn. Stat. 515B.3-113). That law generally doesn't apply to townhome associations created before June 1, 1994 unless they opted in (Minn. Stat. 515B.1-102), so an older association may run under different rules. Your declaration decides whether you need a full homeowners policy or a unit-owner policy like the ones on our condo insurance page. About a third of Eagan households rent, and our Eagan renters insurance guide covers their side.
How exposed is Eagan to hail and windstorms?
Short answerEagan sits in a metro that took a billion-dollar hailstorm in August 2023, NWS reports logged inch-plus hail in neighboring Dakota County cities that evening, and a 2024 storm snapped trees inside Eagan.
The big one was August 11, 2023. The Minnesota Department of Commerce put that storm's damage above $1 billion. The Minnesota DNR's account describes hail from ping-pong ball to baseball size, storms that struck both downtowns, and a 68 mph gust at St. Paul's Holman Field. It doesn't name Eagan or Dakota County. That's why it's worth looking at what the National Weather Service actually logged nearby.
| Date and time | Location (NWS report) | What was reported |
|---|---|---|
| Aug 11, 2023, 5:30 p.m. | 2 miles NNW of Mendota Heights (Ramsey County) | 1.75-inch hail |
| Aug 11, 2023, 5:40 p.m. | 1 mile N of West St. Paul (Dakota County) | 1-inch hail |
| Aug 11, 2023, 5:52 p.m. | Inver Grove Heights (Dakota County) | 1-inch hail |
| Aug 11, 2023, 5:56 p.m. | 1 mile WSW of South St. Paul (Dakota County) | 1.25-inch hail |
| Aug 29, 2024, about 5 p.m. | Eagan, and 3 miles E and SE of Eagan (Dakota County) | Significant tree damage; a large tree and a maple snapped at or near the base |
Those entries come from NWS Twin Cities local storm reports, archived by the Iowa Environmental Mesonet (times converted to Central Daylight Time). No hail report that evening was filed from Eagan itself. That doesn't mean Eagan roofs came through untouched. Storm reports depend on spotters and residents calling them in, so a missing report is not proof of no damage. If you're unsure about your roof after any storm, have it inspected.
Wind matters too: the August 2024 Eagan reports above were all tree damage. When a tree falls on your house or garage, the damage to the structure is typically covered under a standard policy, subject to your deductible. Removing a fallen tree that didn't hit anything is often limited or excluded, so check your policy's debris-removal wording.
Know your deductible before the next storm
Statewide, Minnesota ranked 4th in the nation for hail claims from 2017 to 2019, according to the National Insurance Crime Bureau. Many policies now carry a separate wind/hail deductible set as a percentage, which can mean thousands of dollars out of pocket on a typical Eagan home. A 2024 law (Minn. Stat. 65A.29, subd. 8a) requires 60 days' notice, a plain-language example and at least one flat-dollar option before an insurer moves you to a percentage deductible at renewal. We walk through the math in our Minnesota hail damage guide.
Do you need a permit to replace a roof or siding in Eagan, and will insurance pay for code upgrades?
Short answerYes, Eagan requires a building permit for roof or siding replacement or repair, whoever does the work, so code-required upgrades are part of the job and your policy's code coverage decides who pays for them.
The City of Eagan's Building Inspections page lists "roof replacement/repair," "siding replacement/repair" and "windows/doors" among the projects that need a building permit. It also says permits are required whether a contractor or the homeowner performs the work. Questions go to Eagan Building Inspections at 651-675-5675.
A permit means the finished work is inspected against the current Minnesota code, not the code your house was built under. The Minnesota Department of Labor and Industry's re-siding fact sheet shows what that looks like. It calls for an inspected water-resistive barrier under new siding, and kick-out flashing at roof-to-wall intersections when you re-side, under the 2020 Minnesota Residential Code. A wall sided in 1986 may have neither.
Who pays for the code part
Minnesota law helps here. Under Minn. Stat. 65A.10, where an insurer offers replacement cost coverage, it must pay to repair or rebuild to the minimum code required by state or local authorities. In plain English: if Eagan's inspector requires something your old roof or siding didn't have, replacement cost coverage has to pay for doing it to code, within your limits. Two catches:
- Partial losses cover the damaged portion. The same statute applies replacement cost on a partial loss only to the damaged part, unless your policy says more. Whether a whole elevation gets re-sided so it matches is a policy question, not a legal guarantee.
- ACV settlements change the picture. If your roof is scheduled at actual cash value, depreciation comes off the top. Ordinance-or-law coverage, where available, adds a separate limit for code-driven costs. Look for it on your declarations page.
Our roof claims guide covers 65A.10, matching and ordinance-or-law coverage in more detail.
What water risks in Eagan does a standard home policy leave out?
Short answerFlood and sewer or sump backup, which standard policies typically exclude, and in a city that manages more than 1,200 bodies of water, stormwater can reach homes that are nowhere near a mapped flood zone.
The City of Eagan says on its water resources page that it manages more than 1,200 bodies of water across its 33 square miles, including lakes, ponds and wetlands, and that stormwater drains through a system of street catch basins and underground pipes. City Code Section 11.66 sets floodway and flood fringe zoning districts to reduce losses from periodic flooding. You may have seen another site claim Eagan has "over 1,200 lakes." The city's figure counts bodies of water of every kind, not just lakes.
Heavy rain doesn't need a mapped floodplain to reach a basement. A volunteer CoCoRaHS rain gauge about a mile south-southeast of Eagan recorded 2.11 inches in the report filed the morning of August 18, 2025, per the same NWS storm-report archive. The Minnesota DNR says extreme rain events are becoming more common in Minnesota, that about 50% of flood damage occurs outside mapped flood zones, often from stormwater, and that homeowners policies in most cases don't cover flood.
Sudden water from inside
A supply line or pipe that freezes and bursts is typically covered, if you used reasonable care to keep the heat on or drain the system. See our frozen pipes guide.
Meltwater under the shingles
Interior damage from ice-dam leaks is usually covered under the dwelling. The details are in our ice dam coverage guide.
Sewer, drain or sump backup
Minnesota Commerce says neither flood insurance nor a typical homeowners policy covers sewer backups. You need a separate endorsement.
Rising or surface water
Flood needs its own policy. An NFIP policy usually has a 30-day waiting period, per the NAIC, so buy before spring, not during it.
To check your own address, use FEMA's Flood Map Service Center, which the DNR points homeowners to, or call the city. Minnesota law also requires your insurer to send an annual notice that your homeowners policy doesn't cover flood (Minn. Stat. 65A.302). If your basement is finished or your sump runs hard every spring, ask about raising your sewer and sump backup limit, and see our flood insurance page for how a separate policy fits.
How much does home insurance cost in Eagan, MN, and what moves the price?
Short answerNo regulator publishes an Eagan average; the latest NAIC state data put Minnesota's average HO-3 premium at $1,774 in 2022, and your price depends on rebuild cost, roof, deductible and claims history.
Several lead-generation sites publish "average Eagan premiums" without naming a data source. We don't repeat them. The most recent state comparison comes from the NAIC: an average Minnesota HO-3 premium of $1,774 in 2022 (11th highest in III's ranking of the NAIC data), against $1,569 nationally, as reported by the Insurance Information Institute. Prices have kept moving since. The Federal Reserve Bank of Minneapolis reported in August 2024 that Minnesota homeowners premiums rose 39% over seven years, including 15% in 2023.
One rule that's specific to cities Eagan's size
Minnesota law limits how finely an insurer can slice a large city. Minn. Stat. 72A.20, subd. 13(b) says an insurer must not set more than one geographic rating territory within a first-class city, or a second-class city with 60,000 or more inhabitants by the preceding U.S. decennial census. Eagan counted 68,855 residents in the 2020 census, per QuickFacts. Minnesota's city classes, which cover statutory and home rule charter cities alike, put second class at more than 20,000 and up to 100,000 people (Minn. Stat. 410.01), so Eagan clears that line. In plain English: an insurer can't carve Eagan into separate geographic pricing territories, one part of town against another. Your price still varies by your house, which is why the factors below matter more here than your neighborhood.
| Price factor | What it means for an Eagan home | Can you control it? |
|---|---|---|
| Statewide hail and storm losses | Large metro storm losses like August 2023 can feed into statewide rate increases. | No |
| Rebuild cost | Labor and materials for your square footage and finishes, not the sale price. | Partly |
| Roof age and material | Drives eligibility and whether a roof claim settles at replacement cost or ACV. | Partly |
| Plumbing, electrical, heating and cooling age | Allowed as a rating factor under 72A.20, subd. 13(c). Updates help. | Yes |
| Deductibles | Both the all-perils and the wind/hail deductible move the premium. | Yes |
| Claims history | Paid claims follow you. An inquiry that doesn't lead to a paid claim can't by itself trigger a surcharge (65A.285). | Yes |
What changed recently
Three recent changes matter for Eagan homeowners. The 2024 notice rules for percentage wind/hail deductibles are now in force. A 2025 law requires your insurer to send a copy of your current policy within 21 days if you ask, once per policy period (72A.20, subd. 42). And in February 2026, a homeowners and commercial property insurance task force created by the Legislature recommended that the Department of Labor and Industry fold elements of the IBHS FORTIFIED roofing standards into building codes for new construction. Our statewide homeowners guide tracks all three.
How does Block Agency help Eagan homeowners from its Town Centre Drive office?
Short answerWe're a Farmers Insurance® agency at 1121 Town Centre Drive, Suite 101, Eagan 55123, quoting Farmers first and additional carriers when Farmers isn't the right fit, for homes across Eagan and Dakota County.
Our office is in Eagan, in Dakota County, and a licensed agent reviews every quote. We start with Farmers and, when Farmers isn't the right fit for your house, can look at additional carriers. Availability varies by coverage and location. Our team is bilingual, so we can walk you through a policy in English or Spanish. Se habla español.
To get an accurate Eagan quote on the first pass, bring:
- Your current declarations page. It shows your dwelling limit, both deductibles, and any sewer backup or ordinance-or-law endorsements.
- The roof's year and material. A permit record from the City of Eagan is the cleanest proof of a replacement date.
- Years for system updates. Water heater, furnace, air conditioning, electrical panel and plumbing.
- Square footage and finishes. Including a finished basement, which matters for the backup endorsement.
- Your association documents, for a townhome. The declaration and master policy summary decide which form you need.
If you also drive in Eagan, our Eagan car insurance guide covers the local auto side, and bundling home and auto is a discount you may qualify for, where available. For the wider picture across Burnsville, Apple Valley, Lakeville and the rest of the county, see our Dakota County home insurance guide.
The Bottom Line
Home insurance in Eagan isn't about the city name on the policy. It's about the house: a typical Eagan home built around 1988, a roof that's likely been replaced at least once, systems with their own birthdays, and, for one owner in five, an association master policy that decides where your coverage starts.
So do three things before the next storm season. Find your wind/hail deductible and turn it into a dollar figure. Check whether your policy pays to bring a roof or siding job up to the code Eagan's inspectors will enforce. And close the water gaps a standard policy leaves open, with a sewer and sump backup endorsement and, if your address calls for it, a separate flood policy.
When you're ready, our office is on Town Centre Drive in Eagan. You can start a quote online, call (651) 252-6655, or read how we build policies on our home insurance page. We offer a free coverage review before your renewal — just ask, or we'll reach out.
Related Questions Eagan Homeowners Ask
Do I need a city permit to replace my roof in Eagan after a hail claim?
Yes. The City of Eagan lists roof replacement or repair and siding replacement or repair among the projects that need a building permit, and it says permits are required whether a contractor or the homeowner does the work. A roofer who contracts directly with you also needs a Minnesota residential roofer, remodeler or building contractor license from the Department of Labor and Industry. Because permitted work is inspected to the current code, check whether your policy pays for code-required upgrades before you sign a contract.
Was Eagan hit by the August 11, 2023 hailstorm?
The storm hit the Twin Cities metro hard; the Minnesota Department of Commerce put it above $1 billion in damage. The DNR's account of the storm doesn't name Eagan or Dakota County. National Weather Service storm reports that evening logged 1 to 1.25 inch hail in West St. Paul, South St. Paul and Inver Grove Heights in Dakota County, but none filed from Eagan itself. Storm reports depend on who calls them in, so if you're unsure about your roof, have it inspected and talk to your agent about your policy's claim deadlines.
How do I check whether my Eagan home is in a flood zone?
Look up your address on FEMA's Flood Map Service Center, which the Minnesota DNR points homeowners to, or ask the City of Eagan, whose city code sets floodway and flood fringe districts. Being outside a mapped zone doesn't mean no risk: the DNR says about half of flood damage happens outside mapped flood zones, often from stormwater. Standard homeowners policies typically exclude flood, and NFIP policies usually take 30 days to start.
Is there an official average cost of home insurance in Eagan, MN?
No. Minnesota regulators and the NAIC don't publish a city-level average for Eagan, so be cautious with city figures that don't name their data source. The most recent NAIC state data, via the Insurance Information Institute, put Minnesota's average HO-3 premium at $1,774 in 2022, against $1,569 nationally. Your quote depends on your home's rebuild cost, roof, deductible, claims history and the coverages you choose.
Does homeowners insurance work differently for an Eagan townhome?
Often, yes. About one in five Eagan housing units is a single-family attached home, per Census estimates. Where Minnesota's common interest community law applies and units share walls, siding or roofs, the association's property insurance must include the units, but it need not cover interior finishes, flooring, cabinetry or built-in appliances, and the association can pass its deductible to affected owners (Minn. Stat. 515B.3-113). That law generally doesn't apply to associations created before June 1, 1994 unless they opted in, so read your declaration and the master policy before choosing a homeowners or HO-6 policy.
Can an insurer charge one Eagan neighborhood more than another for home insurance?
Not by drawing territory lines inside the city. Minnesota Statutes 72A.20, subdivision 13 bars an insurer from setting more than one geographic rating territory within a first-class city, or a second-class city with 60,000 or more inhabitants, and Eagan counted 68,855 residents in the 2020 census. Your home's own features, like its roof, systems, rebuild cost and claims history, can still change your price.
Last reviewed by Ryan Block, licensed Minnesota insurance agent, on October 14, 2026. Minnesota statutes cited (65A.10, 65A.285, 65A.29, 65A.302, 72A.20, 410.01, 515B.1-102 and 515B.3-113) were checked against revisor.mn.gov on that date. Local sources checked: U.S. Census Bureau American Community Survey 2020–2024 five-year estimates (tables B25003, B25024, B25034, B25035, B25077) and QuickFacts; City of Eagan Building Inspections and Water Resources pages; National Weather Service Twin Cities local storm reports (via the Iowa Environmental Mesonet); and the Minnesota DNR. Other sources: the Minnesota Department of Commerce, the Department of Labor and Industry, the NAIC, NICB, the Insurance Information Institute and the Federal Reserve Bank of Minneapolis. This guide is general information, not a substitute for reading your own policy. Coverage depends on your specific contract, and not all coverages and discounts are available from every insurer.