What Most People Get Wrong About This
The usual line: "My car sits on the street most of the week, so I only need liability. I barely drive it."
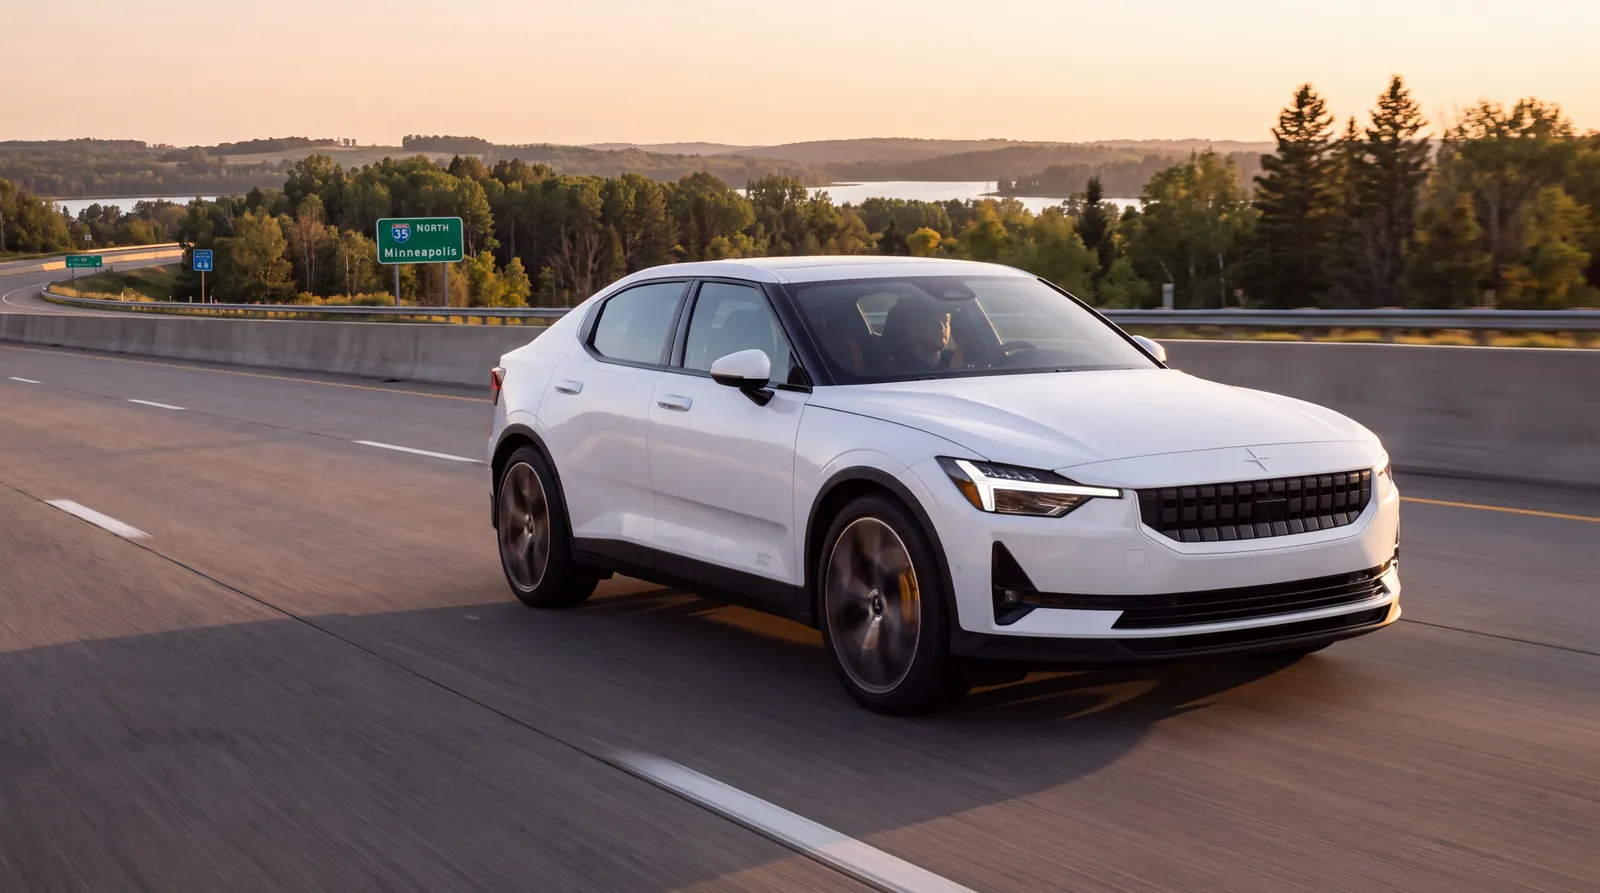
What's actually true: in Minneapolis, a parked car is where a lot of the risk lives. Liability pays for damage you do to other people. It pays nothing when your car is stolen from the curb, when someone saws off the catalytic converter overnight, or when a driver clips your mirror and keeps going. Those losses fall to comprehensive or collision, the two coverages people drop first when a car "mostly just sits." Minnesota's own uninsured motorist law won't fill the gap either: it's written for bodily injury, not for the dent in your door (Minn. Stat. 65B.43).
What to do instead: before cutting coverage on a car you park outside, ask what it would cost you to replace it out of pocket tomorrow. If that number would hurt, comprehensive is usually the last coverage we'd trim.
If you live in Minneapolis, your car spends its life in different conditions from a car in a suburban garage. It parks on the street or in an alley, it moves for every snow emergency, and it sits in the county with the most crashes in Minnesota. None of that changes what state law requires; our Minnesota car insurance guide covers the 30/60/10 minimums, no-fault PIP and UM/UIM in full. What it changes is which optional coverages actually earn their keep in the city, and what a bad week can cost. This guide sticks to the Minneapolis-specific questions: why city rates can differ, how theft and catalytic converter losses are handled, which coverage pays for a parked-car hit, and what the snow emergency rules mean for your wallet. We serve Minneapolis drivers remotely from our office in Eagan, by phone and online.
- Hennepin County crashes
- 17,8882023, DPS Crash Facts
- Metro share of MN auto thefts
- 87%FY2025, BCA
- Kia/Hyundai thefts, Minneapolis
- 2,3402022, MN Attorney General
- Standard city tow
- $222Plus $18 a day storage
Why can car insurance in Minneapolis cost more than in the suburbs?
Short answerInsurers price auto policies partly by where the car is kept, and dense urban areas tend to produce more claims, so a Minneapolis address can rate differently from a suburban one.
The National Association of Insurance Commissioners lists "geographic territory" among the factors that set an auto premium, and puts it plainly: urban areas have more claims than rural areas. It also says claim frequency is the single biggest influence on rating. Minneapolis has more traffic, more parked cars packed close together and more theft than most of the state, and that history shows up in how insurers rate city addresses.
The county numbers make the point. The Department of Public Safety's Minnesota Crash Facts 2023 (Table 1.15) counts 17,888 police-reported crashes in Hennepin County that year, with 53 people killed and 6,524 injured. That's roughly 28% of the 64,744 crashes reported statewide, from a single county. For comparison, Dakota County, where our office sits, reported 6,071.
A rule people misread
You may see it said that Minnesota limits insurers to one rating territory in big cities. That rule is real, but it's narrower than it sounds. Minn. Stat. 72A.20, subd. 13 bars an insurer from setting more than one geographic rating territory inside a city of the first class, or a city of the second class with 60,000 or more inhabitants. But that paragraph sits in a subdivision written for homeowner's insurance, and the words "auto" and "automobile" don't appear in it. So we wouldn't assume a Minneapolis car is priced the same on every block.
How much does vehicle theft in Minneapolis matter for your policy?
Short answerA great deal, because a stolen car is a comprehensive claim, and if you've dropped comprehensive, a theft from a Minneapolis street is a loss you carry yourself.
Theft is the clearest reason city drivers keep comprehensive. When the Kia and Hyundai theft wave hit, the Minnesota Attorney General's office reported (March 2, 2023) 2,340 Kia and Hyundai thefts in Minneapolis in 2022, an 836% increase over the same period in 2021 and 37% of all vehicle thefts in the city that year. The problem was vehicles missing engine immobilizers, the industry-standard anti-theft technology. The manufacturers released software upgrades for some vehicles.
The trend has since turned. The BCA's 2025 Uniform Crime Report (released September 10, 2026) shows motor vehicle theft down 22.4% statewide, from 12,634 in 2024 to 9,803 in 2025. But theft remains concentrated in the metro.
Here's a detail most drivers never notice: Minnesota auto policies with comprehensive coverage help pay for theft prevention. The same report explains that the state's Automobile Theft Prevention Program (Minn. Stat. 65B.84) is funded by a 50-cent-per-vehicle surcharge, which Minn. Stat. 297I.11 applies for every six months of coverage on policies that include comprehensive, for passenger cars, pickups, vans and motorcycles. In fiscal 2025, that program granted the Minneapolis Police Department $332,922.70 for auto theft prevention work.
What comprehensive typically does, and doesn't, do after a theft
- It typically pays for the car, up to its actual cash value, minus your comprehensive deductible, under most policy forms. Check your declarations page for the deductible you chose.
- Damage from a theft attempt, like a broken steering column or a smashed window, is typically a comprehensive claim too.
- Things stolen from inside the car usually aren't. A laptop or a bag taken from the back seat is normally a homeowners or renters claim. Our Minneapolis and Minnesota renters insurance guide explains how that coverage follows your belongings, including the standard form's limit on electronics kept in a car.
- Rental reimbursement is a separate, optional coverage. Without it, the cost of getting around while the claim is open is usually yours.
Is a stolen catalytic converter covered, and what did Minnesota change?
Short answerConverter theft is typically a comprehensive claim, subject to your deductible, and since 2023 Minnesota law makes it much harder to sell a converter that isn't attached to a car.
A catalytic converter is part of the car, so when one is cut out overnight, the loss is a theft, and theft typically falls under comprehensive. The Insurance Information Institute describes comprehensive as covering damage "other than a collision," naming theft and vandalism first. Whether a claim makes sense comes down to the deductible: if yours is high and the repair is close to it, you may decide to pay the shop yourself.
The law changed in 2023. Under Minn. Stat. 325E.21, largely as rewritten by Laws 2023, chapter 15:
- It's unlawful to possess a used catalytic converter that isn't attached to a vehicle, except in listed situations, such as when the converter is marked with the date it was removed and the vehicle's VIN (or a readily linkable alternative number).
- Only registered scrap metal dealers may buy one (unless it's EPA certified for reuse as a replacement part), and a dealer can buy a detached converter only if it's marked that way and, in most cases, the seller shows the vehicle's title or registration.
- Dealers must record the purchase and, since August 1, 2024, enter it in a database available to law enforcement, hold the converter for at least seven days, and wait at least five days to pay.
In plain English, the law tries to make a stolen converter harder to cash in. The state has also supported marking. The Commerce Fraud Bureau's fiscal 2024 theft prevention report says more than 33,500 converter ID labels had been distributed in communities statewide through its pilot. None of this replaces coverage. If you park a higher-clearance vehicle outside in the city, it's one more reason to keep comprehensive.
Street, alley or garage: which coverage pays when your parked car gets damaged?
Short answerTheft, vandalism, falling branches and hail typically go to comprehensive, while a hit-and-run on your parked car is usually a collision claim, because Minnesota uninsured motorist coverage is written for injuries.
Minneapolis drivers park on the street, in alley garages, in shared lots and in ramps downtown. The coverage that answers depends on what hit the car, not where it was parked. Here's how the common city losses usually sort out, subject to your own policy:
| What happened | What usually pays | Worth knowing |
|---|---|---|
| A driver sideswipes your street-parked car and leaves | Collision | Minnesota UM covers bodily injury from hit-and-run drivers (Minn. Stat. 65B.43), not damage to the car |
| The other driver leaves a note, or police identify them | Their liability | Your collision can pay first, minus the deductible, while your insurer pursues them |
| A window is smashed or the car is keyed | Comprehensive | Belongings taken from inside are usually a renters or homeowners claim |
| Hail or a storm-felled branch hits the car | Comprehensive | Street-parked cars have no garage to hide in during a metro hailstorm |
| You slide into a parked car on an unplowed street | Your liability for their car; your collision for yours | Fault applies to vehicle damage even in a no-fault state |
| The car is stolen from an alley or a ramp | Comprehensive | Report it to police right away; your insurer will ask for the report |
That first row is the one that surprises people. Under Minn. Stat. 65B.43, subd. 18, uninsured motorist coverage protects insured people who are entitled to recover damages "for bodily injury" from uninsured or hit-and-run drivers. Damage to your car isn't in that definition, so a driver who dents your door and disappears usually leaves you with a collision claim, or nothing, if you don't carry collision.
Hail deserves a mention in this city. The Minnesota Department of Commerce reported that the August 11, 2023 hailstorm caused more than $1 billion in damage. On a car, hail is a comprehensive claim. If the same storm hit your roof, our guide to hail damage and Minnesota home insurance covers that side.
What does a Minneapolis snow emergency cost you, and is a tow covered?
Short answerA snow emergency tow is parking enforcement, not an accident, so you should expect to pay the city's tow and storage fees yourself rather than through comprehensive or collision.
When the city declares a snow emergency, parking rules run for three days. In the city's March 14, 2026 announcement, they read like this:
- Day 1 (starting 9 p.m.): don't park on either side of a Snow Emergency route until 8 a.m., or until the street is fully plowed.
- Day 2 (8 a.m. to 8 p.m.): don't park on the even-numbered side of non-Snow Emergency routes, or on either side of a parkway, until 8 p.m. or until it's fully plowed.
- Day 3 (8 a.m. to 8 p.m.): don't park on the odd-numbered side of non-Snow Emergency routes until 8 p.m. or until that side is fully plowed.
The city warns that cars left in the way risk a ticket and a tow to the impound lot. The Minneapolis Impound Lot (page updated January 16, 2026) lists a $222 standard tow charge, $18 a day in storage, and a $6 notification letter. The lot is at 50 Van White Memorial Blvd, and you can search for a towed car online or call 612-673-5777. The city's snow emergency line is 612-348-SNOW (7669).
Winter also brings the warm-up problem. A car left running and unlocked at the curb is an easy theft. Minneapolis separately limits idling to three minutes, except in traffic, according to the city's idling notice. Keep the keys with you, and keep comprehensive on the policy.
Do rideshare drivers and low-mileage Minneapolis households need a different policy?
Short answerRideshare and delivery drivers need coverage built for app time, while households that drive less should tell their insurer about it and ask whether mileage-based pricing fits.
Rideshare and delivery. City streets are full of app drivers, and a personal auto policy can exclude the time the app is on. Minnesota sets specific coverage for transportation network company drivers in Minn. Stat. 65B.472. We cover the required limits in our statewide auto guide; the short version is to ask about a rideshare endorsement before your first shift.
Car-light households. Many Minneapolis residents live car-light. The city's Minneapolis 2040 plan, citing 2014–2018 Census American Community Survey estimates, says 16.5% of people in Minneapolis live in a household without a car. If your household has one car and a transit pass, mileage matters to your price. The NAIC notes that higher annual mileage means higher exposure to risk, and that usage-based programs can measure how much you actually drive. Give your insurer an honest annual mileage figure, and ask whether a usage-based program is offered, where available.
What low mileage shouldn't do is talk you out of comprehensive. A car that rarely moves is still parked outside every night.
How we serve Minneapolis from Eagan
Block Agency doesn't have a Minneapolis office, and we won't pretend otherwise. Our office is at 1121 Town Centre Drive, Suite 101, in Eagan, and we serve Minneapolis drivers by phone, email and online quote, under the same Minnesota license. We start with Farmers and, when Farmers isn't the right fit for your household, can look at additional carriers. Our bilingual team works in English or Spanish. Se habla español. If you also have a place in the south metro, or a family member there, our Eagan car insurance guide covers the suburban side of the same questions.
The Bottom Line
Car insurance in Minneapolis starts with the same legal minimums as the rest of the state. What's different is where the risk sits. In the city, much of it hits the car while it's parked: theft, a cut catalytic converter, a hit-and-run on a narrow street, a hailstorm with no garage nearby. Those losses are typically comprehensive or collision claims, and Minnesota's uninsured motorist coverage won't pay for the car itself.
So if you do one thing after reading this, check whether your policy still carries comprehensive and collision, and whether the deductibles are numbers you could pay this week. Then put the snow emergency hotline in your phone, because the $222 tow and the daily storage fee are costs no auto policy is built to pay.
When you're ready, compare options on our auto insurance page or start a quote. Driving out of the city in the fall? Our guide to hitting a deer in Minnesota covers the other comprehensive claim the state is known for.
Related Questions Minneapolis Drivers Ask
Does car insurance pay to get my car out of the Minneapolis impound lot after a snow emergency tow?
Usually not. A snow emergency tow is parking enforcement, not physical damage, so it isn't what comprehensive or collision coverage is built to pay. The Minneapolis Impound Lot lists a $222 standard tow charge plus $18 a day in storage (page updated January 16, 2026). Roadside-assistance add-ons are generally written for breakdowns, so check your own endorsement. If the car was damaged during the tow, photograph it before leaving the lot.
Is a Kia or Hyundai stolen in Minneapolis covered by insurance?
It typically is if the policy carries comprehensive coverage, which pays for theft up to the car's actual cash value, minus your deductible, under most policy forms. Liability-only policies don't cover theft of your own car. The Minnesota Attorney General reported 2,340 Kia and Hyundai thefts in Minneapolis in 2022, tied to vehicles missing engine immobilizers. Ask your dealer whether the manufacturer's anti-theft software upgrade applies to your vehicle.
Who pays if someone hits my car parked on a Minneapolis street and drives off?
Usually your own collision coverage, minus your deductible. Minnesota's uninsured motorist coverage protects people who are entitled to damages for bodily injury from uninsured or hit-and-run drivers (Minn. Stat. 65B.43, subd. 18), so it doesn't pay to repair the car. If the driver is later identified, your insurer can pursue their liability coverage. File a police report and photograph the damage right away.
Is a catalytic converter stolen in Minneapolis covered by car insurance?
Converter theft is typically a comprehensive claim, subject to your comprehensive deductible, so whether to file depends on how the repair cost compares with that deductible. Since 2023, Minn. Stat. 325E.21 makes it unlawful, with limited exceptions, to possess a detached used converter unless it's marked with the removal date and the vehicle's VIN or a linkable number, and generally only registered scrap dealers may buy one.
Do Minneapolis drivers pay more for car insurance than drivers in the suburbs?
They can. Insurers rate auto policies partly by geographic territory, and the NAIC notes that urban areas generate more claims than rural ones. Hennepin County alone reported 17,888 police-reported crashes in 2023, about 28% of Minnesota's total. Minnesota's one-territory rule for large cities in Minn. Stat. 72A.20, subd. 13 sits in a homeowner's insurance subdivision and doesn't mention auto. No regulator publishes a Minneapolis average, so compare quotes at your own address.
Can an Eagan insurance agency insure my car if I live in Minneapolis?
Yes. A Minnesota-licensed agent can write auto coverage for a car garaged anywhere in the state. Block Agency serves Minneapolis drivers from its office at 1121 Town Centre Drive, Suite 101, in Eagan, by phone, email and online quote, starting with Farmers Insurance and looking at additional carriers when Farmers isn't the right fit. Call (651) 252-6655. Se habla español.
Last reviewed by Ryan Block, licensed Minnesota insurance agent, on October 14, 2026. Minnesota statutes cited (65B.43, 65B.472, 65B.84, 297I.11, 72A.20 and 325E.21) were checked against revisor.mn.gov on that date. Local facts come from the City of Minneapolis (snow emergency announcement, March 14, 2026; impound lot fees, updated January 16, 2026; idling notice; Minneapolis 2040 plan), the Minnesota Department of Public Safety (Crash Facts 2023; BCA 2025 Uniform Crime Report; BCA Automobile Theft Prevention Program report, September 30, 2025), the Minnesota Department of Commerce (FY2024 theft prevention report; April 2024 storm release) and the Minnesota Attorney General (March 2, 2023). Premium trends come from the Federal Reserve Bank of Minneapolis (May 2026) and the NAIC. This guide is general information, not a substitute for reading your own policy. Coverage depends on your specific contract, and not all coverages and discounts are available from every insurer.